Measuring portfolio concentration risk
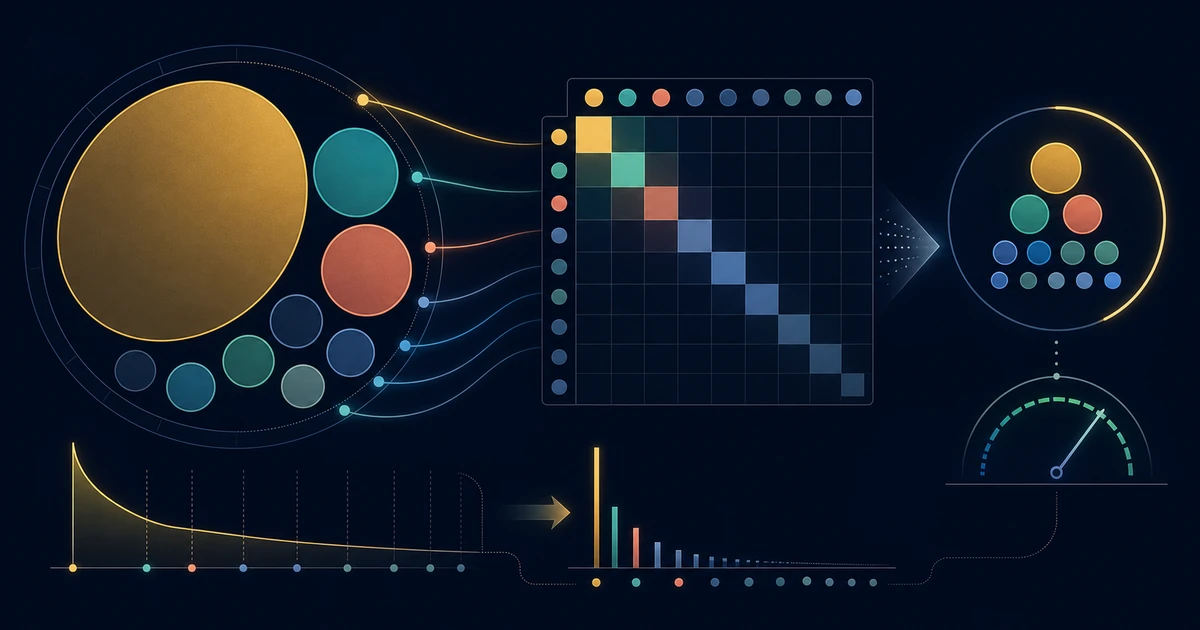
Start with current market values in one currency. Position weights show where your money is concentrated; the number of ticker symbols alone cannot do that. Cash is separate from invested holdings in the calculations below.
Why counting holdings fails
The intuition that more holdings means less risk is roughly right and precisely useless. Consider two portfolios, both holding ten stocks. The first splits capital evenly, ten percent each. The second holds sixty percent in one name and spreads the remaining forty percent across nine others.
Maximum position weight
The simplest useful measure: what fraction of total value sits in the single largest holding.
max_weight = max(valuei) / Σ valuei
The Herfindahl-Hirschman Index
The HHI comes from antitrust economics, where regulators use it to measure how concentrated an industry is among its competitors. The same mathematics applies cleanly to a portfolio: square every weight, then sum the squares.
HHI = Σ wi² where wi = valuei / total value
The index is bounded in a useful way:
| Portfolio | HHI |
|---|---|
| Single holding | 1.00 |
| Two holdings, equal | 0.50 |
| Ten holdings, equal | 0.10 |
| Fifty holdings, equal | 0.02 |
The pattern is visible: for N equally weighted holdings, HHI equals 1/N. That relationship is what makes the next metric possible.
Effective number of positions
Neffective = 1 / HHI
The reciprocal of HHI is the number of equally weighted positions with the same weight concentration. It is not the number of independent investments and does not predict how a portfolio will perform.
A worked example
Take a three-position technology portfolio:
| Holding | Value | Weight | Weight² |
|---|---|---|---|
| AAPL | $25,000 | 45.45% | 0.2066 |
| MSFT | $22,000 | 40.00% | 0.1600 |
| NVDA | $8,000 | 14.55% | 0.0212 |
| Total | $55,000 | 100% | 0.3878 |
Using the unrounded weights gives HHI 0.3878 and 2.58 effective positions. The largest position is 45.45% of invested value. Those are concentration measurements; they do not establish that the three stocks have the same risk or will move together.
The concentration these metrics miss
These numbers describe position sizing, not total investment risk. They do not measure volatility, correlations or the underlying securities inside funds. Equally sized stocks can still share sector or economic exposures. A small holding can also be very volatile.
Funds are treated as individual positions. Underlying holdings and overlap between funds are not analysed; concentration figures describe fund allocations, not diversification across underlying issuers.
What is a good portfolio score? →
For developers
Check your own portfolio
Free evaluation. No account required.
Get my portfolio score →Create a free account to save up to 10 portfolios, reopen the holdings and run a fresh evaluation. You choose what is saved.
Create a free account →